At a Glance
- Market value: USD 1,940 million in 2025
- Forecast value: USD 3,005 million by 2032
- Forecast CAGR: 6.45% (2025-2032)
- Historical CAGR: 19.84% (2020-2025)
- Operational airports: 164 in 2025, up from 74 in 2014
What Is Changing in the India Ground Handling Services Market?
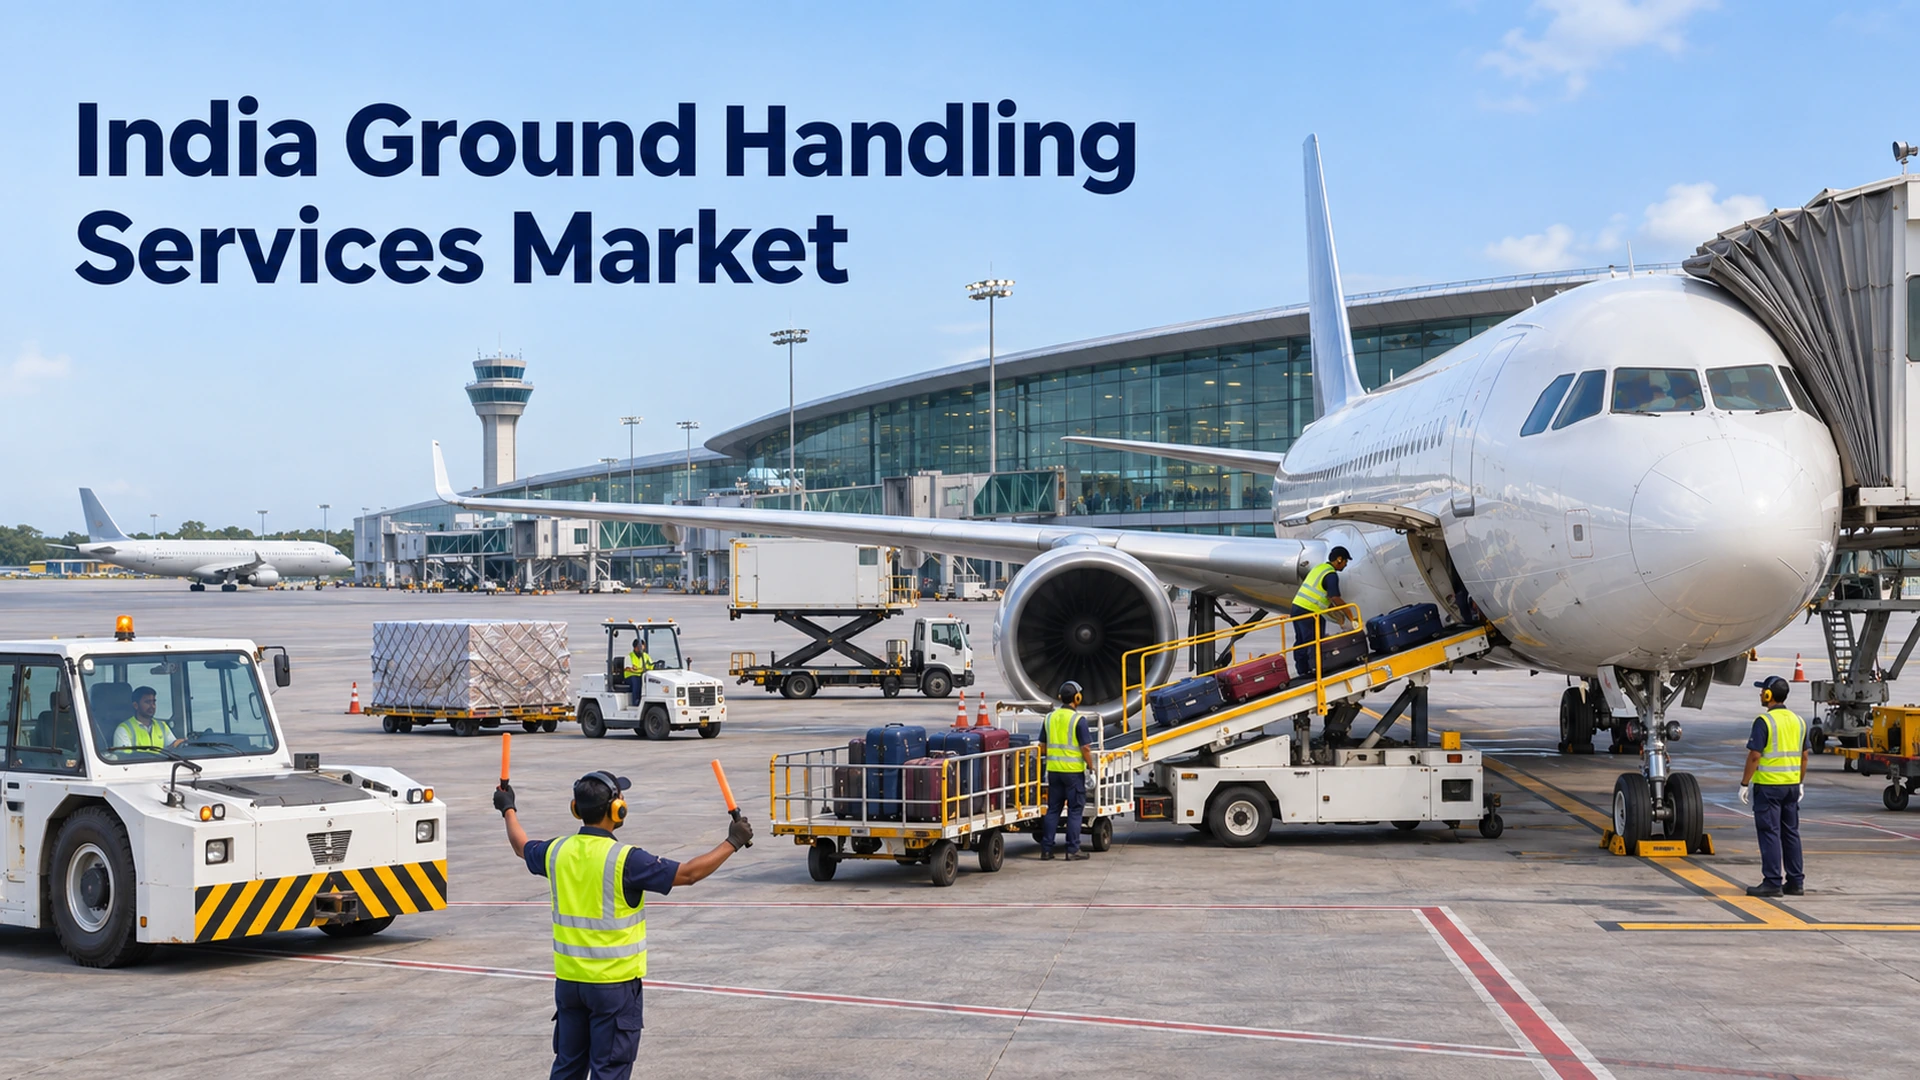
The market is shifting from post‑pandemic recovery to a structural expansion driven by rapid airport network growth and the rollout of electric ground support equipment (GSE). India’s operational airports have more than doubled since 2014, reaching 164 in 2025, which creates new concession opportunities and demands scalable multi‑station handling models. At the same time, the Noida International Airport concession in 2024 mandated electric‑powered GSE, signaling a sustainability‑focused procurement trend that is reshaping capital allocation for handlers. India Ground Handling Services Market is therefore poised for a new growth phase beyond the recovery‑led surge of the early 2020s.
Why Is Airport Network Expansion Important for the India Ground Handling Services Market?
Impact on Market Demand
Passenger throughput stood at 412 million in FY2025 and is projected to reach 665 million by FY2031. The expanding network of 164 airports directly translates into higher check‑in, boarding, baggage reconciliation and ramp activity across both major gateways and emerging regional stations. This demand base underpins the forecast revenue rise to USD 3,005 million by 2032, outpacing the 5.22% volume CAGR of aircraft turnarounds.
Impact on Competition
Handlers with national coverage, safety clearances and scalable labor pools are positioned to capture disproportionate incremental revenue. Multi‑airport operators such as Bird Group, which already spans 15 airports and processes over 4,400 flights monthly, can leverage economies of scale to win new concessions, especially at greenfield airports where competitive structures are still forming.
Impact on Market Growth
The network expansion also fuels ancillary services—cargo & mail handling, specialized ULD management, and electric‑fleet maintenance—adding higher‑margin revenue per movement. The report notes that value growth is expected to modestly outpace volume growth as international traffic, cargo intensity and technology‑enabled service packages increase blended revenue per turnaround.
What Does the Ken Research Report Reveal About Market Opportunities?
Fastest‑Growing Segment: Cargo & Mail Handling
Air cargo volumes rose from 2.53 million tonnes in FY2015 to 3.72 million tonnes in FY2025. This growth supports differentiated economics for ULD handling, perishables, and express cargo, positioning cargo & mail handling as the fastest‑growing segment.
Technology Opportunity: Electric Ground Support Equipment
The Noida concession’s requirement for electric GSE creates a financing and fleet‑renewal opportunity. Scaled handlers can replicate electric‑fleet standards across multiple concessions, driving procurement efficiencies and meeting emerging sustainability mandates.
Regional Opportunity: UDAN‑Enabled Airports
Under the UDAN scheme, 619 routes and 88 airports were operationalized by April 2025. Regional airports demand standardized, lower‑cost service packages, opening a market for modular contracts and cluster‑based handling platforms.
What Does the Market Shift Mean for Businesses?
Aftermarket and Recurring Revenue Opportunities
Interpretation: The report suggests that electric GSE deployment will generate recurring revenue streams through maintenance contracts, charging infrastructure services, and fleet‑upgrade financing, especially for handlers with a national footprint.
Market Adoption and Execution Challenges
Interpretation: Compliance burdens—such as DGCA safety clearance and concession royalty structures (e.g., 45% revenue share at Goa)—pose margin pressures. Labor intensity remains a risk, as illustrated by the Mumbai disruption that delayed 31 departures and affected baggage delivery on multiple flights.
What Should India Ground Handling Services Participants Watch Next?
- Progress of electric GSE mandates at upcoming greenfield airports
- Regulatory developments around DGCA safety clearance and concession royalty rates
- Expansion of UDAN routes and the resulting demand for regional handling platforms
- Air cargo growth trends and specialist handling service adoption
- Competitive moves by multi‑airport operators securing national concessions
How Can Businesses Apply These Market Findings?
Businesses looking to capitalize on the India Ground Handling Services market should first align their operational footprint with the projected airport network expansion. The report indicates that the number of operational airports will rise from 164 in 2025 to 704 by 2032, creating a vast array of concession opportunities. Firms that already possess national coverage and safety clearances can leverage economies of scale to bid for new greenfield airports, especially those under the UDAN scheme, where standardized, lower‑cost service packages are in demand. By establishing cluster‑based handling platforms, operators can reduce per‑airport fixed costs while maintaining service quality across multiple sites.
Second, the shift toward electric ground support equipment (GSE) presents a dual revenue stream. The Noida International Airport concession in 2024 mandated electric‑powered GSE, signaling a broader sustainability trend. Companies that invest in electric fleets early can benefit from recurring maintenance contracts, charging infrastructure services, and fleet‑upgrade financing. Moreover, the capital allocation for electric GSE is expected to reshape the market, allowing handlers with modern equipment fleets to capture higher margins on each turnaround. Integrating electric GSE across multiple concessions not only meets regulatory mandates but also positions firms as leaders in green operations, potentially attracting airlines seeking to reduce their carbon footprint.
Third, the fastest‑growing segment—cargo and mail handling—offers differentiated economics that can boost overall revenue per movement. Air cargo volumes are projected to reach 5.49 million tonnes by 2032, up from 3.72 million tonnes in 2025. Operators that develop specialized ULD management, perishables handling, and express cargo services can tap into this high‑margin niche. By bundling cargo services with passenger handling, firms can create comprehensive, value‑added packages that increase blended revenue per turnaround, thereby outpacing the 5.22% volume CAGR of aircraft turnarounds.
Fourth, businesses must navigate compliance and labor intensity risks. The DGCA safety clearance process and concession royalty structures—such as the 45% revenue share at Goa—can exert margin pressure. Additionally, labor disruptions, exemplified by the Mumbai incident that delayed 31 departures, highlight the need for robust workforce management and contingency planning. Firms that invest in workforce productivity tools, cross‑training, and digital workflow solutions will be better positioned to maintain service levels and protect margins in a highly competitive environment.
Finally, continuous monitoring of regulatory developments and market dynamics is essential. Key areas to watch include the rollout of electric GSE mandates at upcoming greenfield airports, changes in DGCA safety clearance requirements, and the expansion of UDAN routes. By staying ahead of these trends, operators can secure early access to new concessions, negotiate favorable terms, and position themselves as preferred partners for airlines and airport authorities alike.
Conclusion: India Ground Handling Services Market Outlook
The India Ground Handling Services Market is set to grow to USD 3,005 million by 2032, driven by a 6.45% CAGR, expanding airport infrastructure, rising passenger and cargo volumes, and a shift toward electric GSE. Operators that can scale across the growing network, meet stringent safety and sustainability standards, and capture ancillary cargo and aftermarket revenue will be best positioned to thrive in this evolving landscape.