At a Glance
- Market value: USD 253 million in 2025
- Projected value: USD 559 million by 2032
- Forecast CAGR: 12.00% (2025-2032)
- Active accounts: 950,000 in 2025, rising to 1.63 million by 2032
- Revenue per account: USD 266 in 2025, increasing to USD 343 in 2032
What Is Changing in the Indonesia Agritech Market?
The Indonesia Agritech Market is poised to more than double its size, expanding from USD 253 million in 2025 to USD 559 million by 2032, driven by a robust 12.00% forecast CAGR. This acceleration reflects a shift from pure account acquisition toward higher‑value service attachment, as platforms bundle financing, analytics, traceability and equipment services to lift average revenue per active farm from USD 266 to USD 343.
Why Is Premiumization Important for the Indonesia Agritech Market?
Impact on Market Demand
Demand is anchored in an under‑penetrated base of 28.42 million agricultural households, yet only 950,000 active accounts were recorded in 2025. The low single‑digit penetration creates ample room for field‑agent models that lower onboarding costs and aggregate producer demand. As platforms attach higher‑margin services, the blended revenue per account rises, fueling demand for bundled solutions that improve farm productivity and financial inclusion.
Impact on Competition
Competition is intensifying around the dominant “Market Access and Farm‑as‑a‑Service” segment, which combines procurement, distribution and buyer aggregation. Players that can demonstrate verified transaction volumes and recurring enterprise revenue—through commissions, financing spreads and paid data services—are gaining a competitive edge. The market’s fragmentation (283 tracked startups) and the emergence of sector‑specific networks outside Java further pressure incumbents to differentiate via integrated service stacks.
Impact on Market Growth
Growth is propelled by digital market‑access initiatives, food‑security programs and the attachment of financing, analytics and traceability services. The forecasted 12.00% CAGR outpaces the historical 9.06% CAGR (2020‑2025), indicating that platforms capable of documenting real transactions and active farms are capturing a larger share of the digital agriculture GMV, which stood at USD 1.5 billion in 2025.
What Does the Ken Research Report Reveal About Market Opportunities?
Fastest‑Growing Segment: Market Access and Farm‑as‑a‑Service
This solution type remains commercially central, merging procurement, distribution and buyer aggregation within a single revenue relationship. Its dominance is reinforced by a 15% blended take rate in 2025, enabling platforms to monetize commissions, financing spreads and data verification fees.
Emerging Opportunity: Market Linkage and Traceability
Traceability solutions are expected to expand fastest as agribusiness buyers demand verifiable sourcing and chain‑of‑custody data. Platforms that embed production evidence with procurement commitments can capture recurring enterprise revenue and reduce reliance on consumer‑commerce margins.
Bank‑Integrated Agricultural Finance
Bank partnerships are critical after regulatory setbacks that saw licenses revoked for TaniFund (May 2024) and Crowde (Nov 2025). A USD 250 billion (IDR) working‑capital facility provided to Chickin illustrates how regulated lenders can fund input procurement while retaining credit oversight, creating a scalable financing conduit for millions of farms.
Vertical IoT and Farm Automation
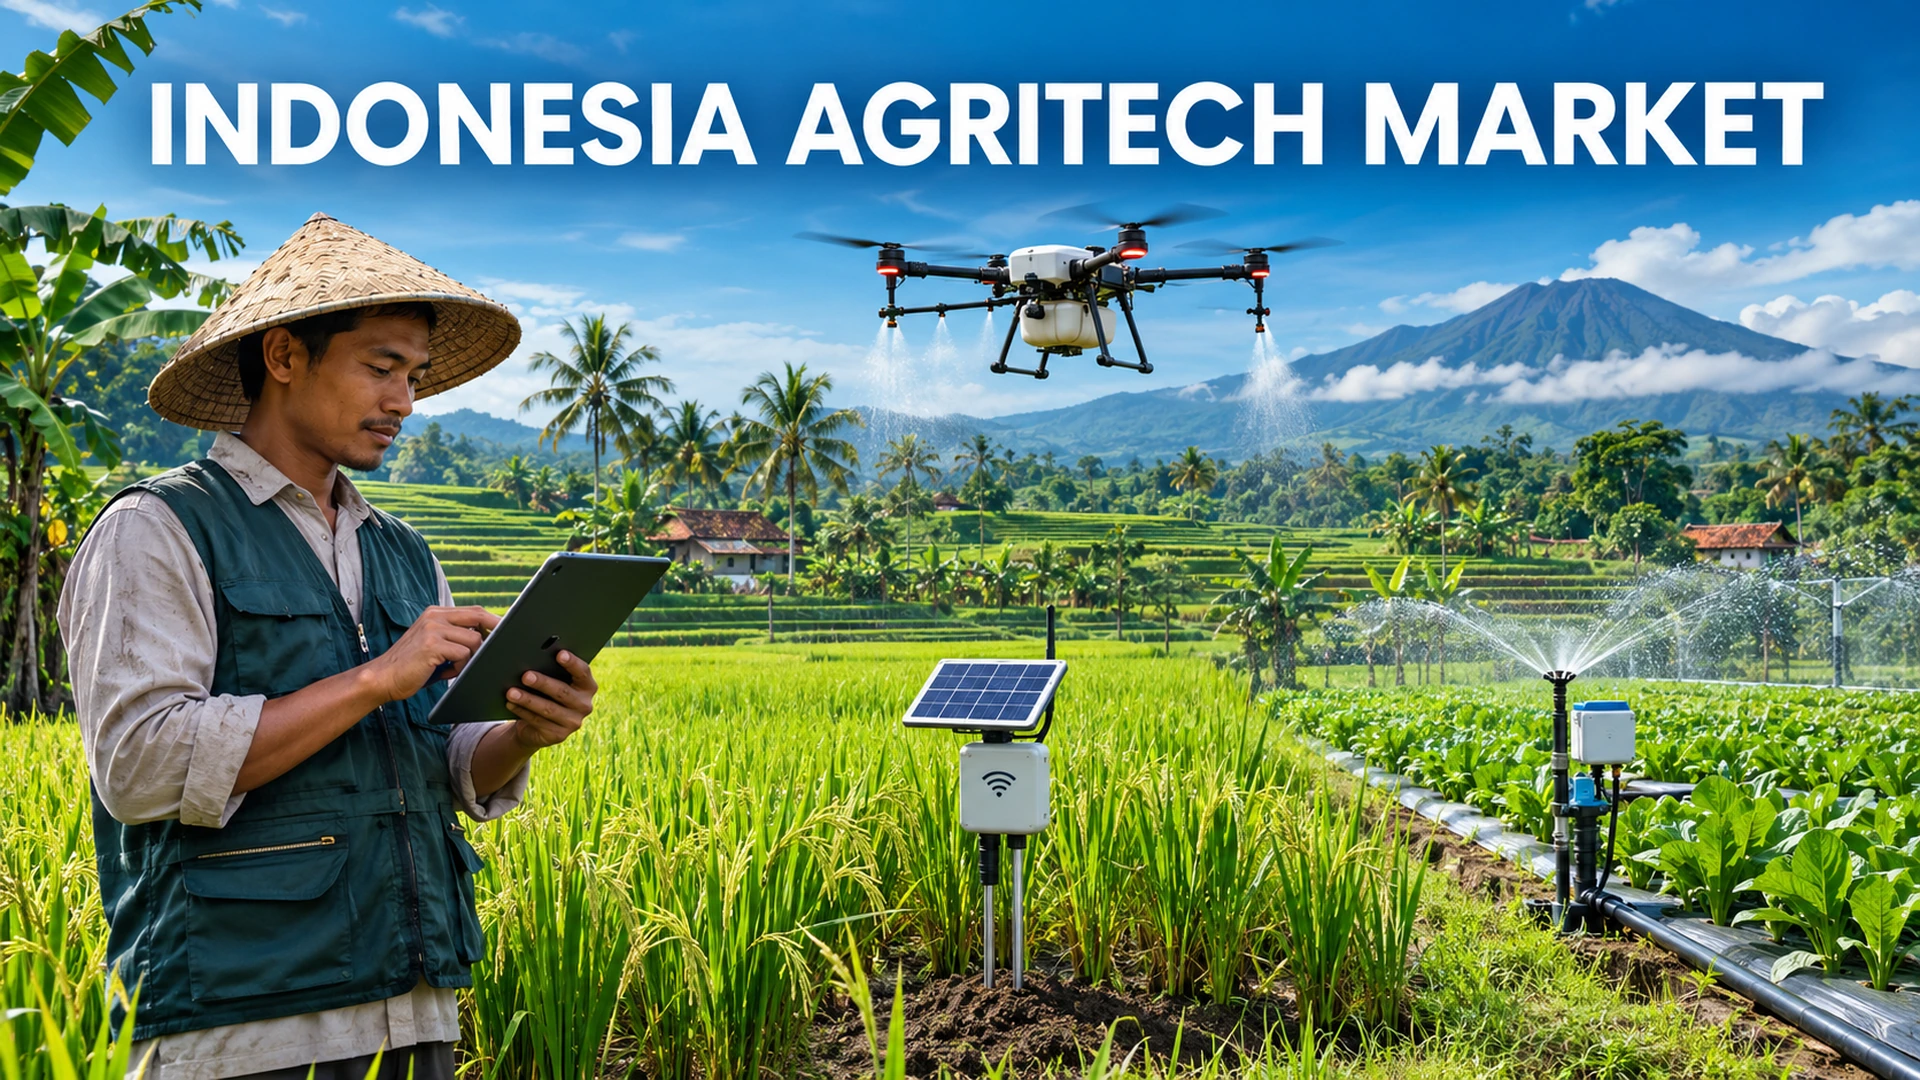
IoT deployments, such as eFishery’s verified feeder base of approximately 24,000 units, link farm performance with downstream fulfillment. The projected revenue per account of USD 343 by 2032 hinges on paid analytics, equipment services and outcome‑linked contracts that supplement transaction commissions.
What Does the Market Shift Mean for Businesses?
Aftermarket and Recurring Revenue Opportunities
Interpretation: The report suggests that platforms focusing on bundled services—financing, analytics, traceability and equipment leasing—will capture higher per‑account revenue, turning one‑time transactions into recurring streams. Companies that can certify active installations and audit marketplace throughput will be better positioned to command premium take rates.
Market Adoption and Execution Challenges
Interpretation: While the upside is tied to government procurement, bank co‑lending and scalable IoT, downside risks remain concentrated in regulatory enforcement, weak farmer repayment performance and investor caution. Executives must prioritize robust field‑audit mechanisms and transparent data pipelines to mitigate governance and financing risks.
What Should Indonesia Agritech Participants Watch Next?
- Regulatory developments affecting agricultural fintech licensing
- Scaling of bank‑integrated financing facilities and their impact on farmer credit access
- Adoption rates of IoT and edge‑deployment models across poultry, aquaculture and crop segments
- Evolution of traceability standards demanded by institutional buyers
- Investor sentiment shifts following governance‑related funding declines
How Can Businesses Apply These Market Findings?
Interpretation: Companies seeking to capture the projected expansion to USD 559 million by 2032 should prioritize scaling active accounts while simultaneously increasing revenue per account. The data shows active accounts rising from 950,000 in 2025 to roughly 1.63 million in 2032, an 8.00% CAGR, yet blended revenue per account climbs from USD 266 to USD 343, a 3%‑4% annual uplift. Interpretation: Firms that invest in field‑agent networks or mobile onboarding tools can accelerate account acquisition, but the true value driver will be the ability to attach higher‑margin services—financing, analytics, traceability, and equipment leasing—to each farm. By bundling these services, platforms convert low‑margin transaction commissions into recurring, premium‑priced revenue streams.
Interpretation: To operationalize premiumization, businesses must build end‑to‑end digital stacks that link input procurement, production monitoring, and downstream buyer access. The dominant “Market Access and Farm‑as‑a‑Service” segment already demonstrates a 15% blended take rate in 2025, indicating that integrated procurement and distribution channels generate measurable fees. Interpretation: Enterprises that embed verified IoT sensors, such as eFishery’s feeder units, and couple them with data‑driven financing offers can command higher take rates while providing lenders with granular underwriting data, thereby reducing credit risk and improving loan recovery.
Interpretation: Geographic focus remains critical. Java continues to host the majority of agritech firms, investors, and financial partners, but the report highlights the emergence of sector‑specific networks beyond the island. Companies that replicate the Java model—leveraging local cooperatives, extension services, and regional distribution hubs—can unlock untapped demand among the 28.42 million agricultural households. Interpretation: A decentralized rollout that pairs regional agribusiness aggregators with national fintech partners will expand market reach without inflating customer acquisition costs, preserving the margin advantage of premium services.
Interpretation: Risk mitigation should be embedded in growth plans. The forecast notes downside exposure to regulatory enforcement, weak farmer repayment, and investor caution. Platforms that institute transparent field‑audit mechanisms, real‑time transaction verification, and third‑party certification of traceability data will be better positioned to navigate regulatory scrutiny. Interpretation: By aligning with government food‑security programs and securing bank‑integrated financing facilities—similar to the USD 250 billion working‑capital facility supporting Chickin—companies can diversify funding sources and demonstrate compliance, thereby attracting more conservative capital.
Interpretation: Finally, strategic partnerships will accelerate the transition from pure account growth to revenue premiumization. Collaborations with banks enable co‑lending models that reduce the platform’s credit exposure while extending financing to millions of farms. Joint ventures with logistics providers ensure reliable downstream delivery, reinforcing the value proposition of market‑access services. Interpretation: Firms that orchestrate multi‑party ecosystems—combining fintech, IoT, logistics, and traceability—will create defensible moats, capture a larger share of the projected USD 1.5 billion digital agriculture GMV, and sustain the 12.00% forecast CAGR through 2032.
Conclusion: Indonesia Agritech Market Outlook
The Indonesia Agritech Market is on a trajectory to more than double its 2025 size by 2032, underpinned by a 12.00% CAGR and a clear premiumization trend. Platforms that successfully attach financing, analytics and traceability to a growing base of active farms will unlock higher revenue per account, while disciplined governance and bank partnerships will be essential to sustain growth and mitigate risk.